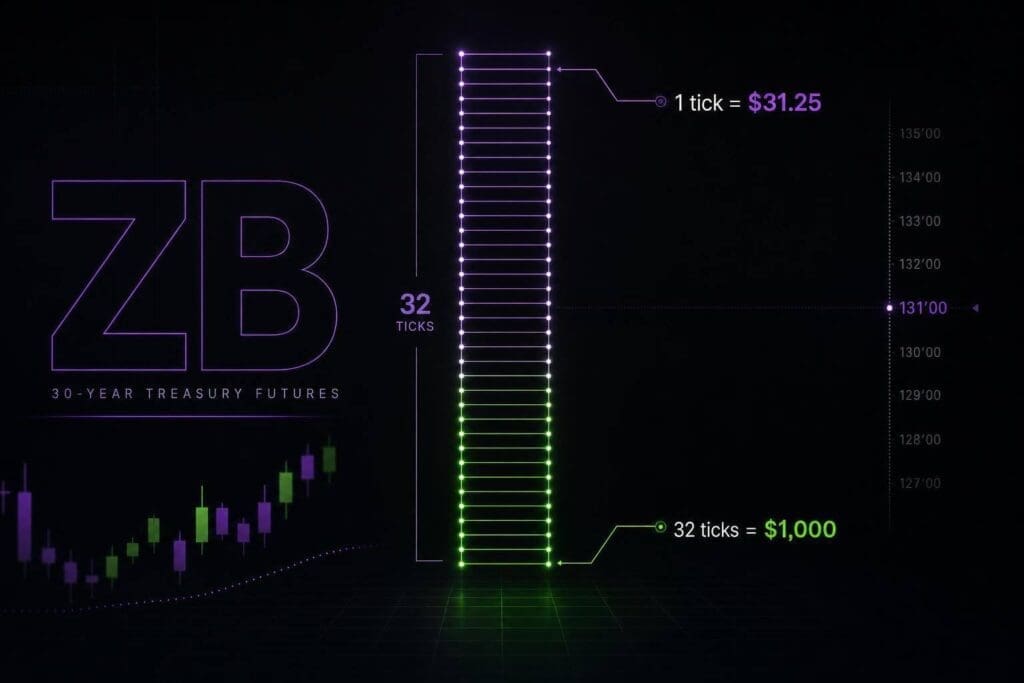
ZB moves in 1/32-point increments, and each tick is worth $31.25 per contract. That’s the number that matters when you’re setting stops, sizing positions, or figuring out whether a trade is worth taking at all. If you trade bond futures, small chart moves can turn into big dollar swings fast.
I’ll keep this tight: what ZB is, how the quote format works, what a point is worth, and the math you should do before you click buy or sell. If you trade in a prop account, this is the stuff that keeps a dumb sizing mistake from wrecking your day.
How to Calculate Profit or Loss on Futures Contracts
sbb-itb-46ae61d
Introduction
ZB is the 30-Year Treasury Bond futures contract on CBOT/CME, with a notional value of $100,000 per contract. That setup drives everything from the way ZB is quoted to how you size risk.
ZB trades in 32nds of a point. Each tick is worth $31.25, and 32 ticks make 1 full point, or $1,000 per contract[1]. That’s the math behind your stops, targets, and how many contracts you can carry without doing something dumb.
Next, the contract specs and trading hours show exactly how ZB trades.
ZB Contract Specs at a Glance
Here are the core ZB contract specs you need to know before you trade it.
Key Specifications Table
| Specification | Detail |
|---|---|
| Symbol | ZB |
| Exchange | CBOT / CME Group |
| Contract Size | $100,000 face value |
| Price Quotation | Points and 32nds of a point (for example, 115-16) |
Trading hours matter next, because ZB fills live and die by the CME session window.
How ZB Prices Are Quoted
ZB uses fractional pricing, not decimal pricing. That matters right away, because your stops, targets, and order entries all start with the quote format.
What a Quote Like 115-16 Means
115-16 means 115 whole points plus 16/32. In decimal form, that’s 115.500.
Quoted Format vs. Decimal Conversion
To convert a ZB quote into decimals, divide the 32nds by 32 and add that number to the whole price. Simple math, but it’s easy to screw up if you’re moving fast.
Use the table below to line up the quoted format with the decimal price:
| Price | Decimal Equivalent | Ticks from 115-00 |
|---|---|---|
| 115-00 | 115.000 | 0 |
| 115-08 | 115.250 | 8 |
| 115-16 | 115.500 | 16 |
| 115-24 | 115.750 | 24 |
| 116-00 | 116.000 | 32 |
Common Order-Entry Mistakes
The big mistake is treating a fractional quote like a decimal quote. That’s how bad entries happen.
Check your platform before you place anything. Make sure you know whether ZB is showing in 32nds or decimals. Then confirm what your DOM is displaying, and translate ticks into dollar P&L using a futures trading profit calculator on purpose, not in your head while the market is moving.
Once the quote format is locked in, the next step is turning ticks into dollar P&L.
How to Calculate ZB Tick Value and P&L
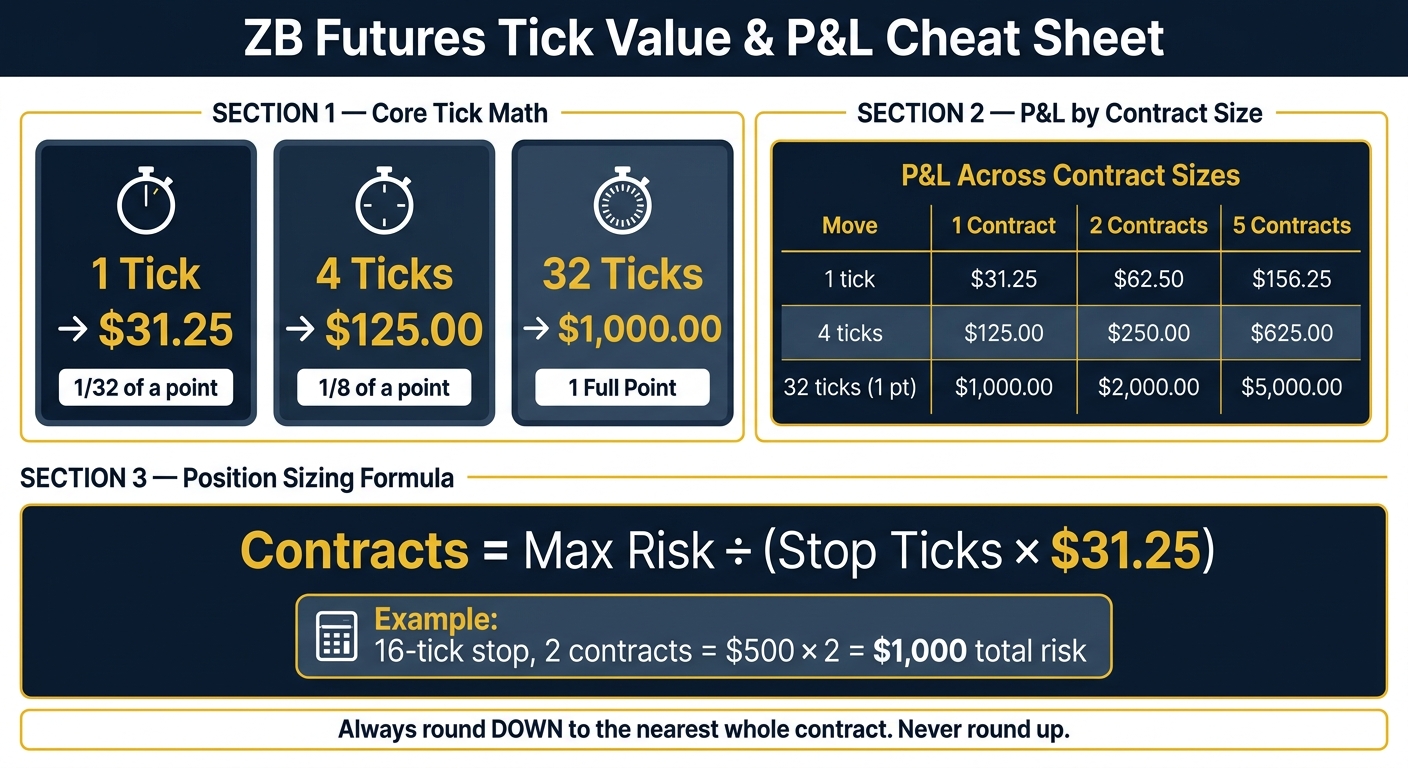
ZB Futures Tick Value & P&L Cheat Sheet
ZB trades in 32nds, so you need to turn each price move into dollars before you set a stop or target. If you skip that step, your risk gets out of hand fast.
The ZB P&L Formula
P&L = ticks × $31.25 × contracts
Use this conversion before placing stops or targets.
Examples: 1 Tick, 4 Ticks, and 1 Full Point
Here’s the math in plain English: 1 tick = $31.25, 4 ticks = $125.00, and 32 ticks = $1,000.00 per contract.
That’s why ZB can hit hard. If you’re trading this volatility on a Funded Futures Network account, understanding these swings is critical for drawdown management. A move that looks small on the chart can still mean real money.
P&L Across Multiple Contracts
Use this table to see how the same move changes with position size.
| Move | 1 Contract | 2 Contracts | 5 Contracts |
|---|---|---|---|
| 1 tick | $31.25 | $62.50 | $156.25 |
| 4 ticks | $125.00 | $250.00 | $625.00 |
| 32 ticks (1 point) | $1,000.00 | $2,000.00 | $5,000.00 |
That dollar math is what you use next to size risk from your stop distance. A 4-tick stop on 5 contracts isn’t just “a little room.” It’s $625.00 at risk.
How to Size a ZB Position Using Tick Risk
Use the tick value to turn your stop distance into dollar risk. Then size your contracts from the max amount you’re willing to lose on the trade.
A Simple Position-Sizing Formula
Contracts = Maximum Acceptable Risk ÷ (Stop Ticks × $31.25)
Round down to the nearest whole contract. No exceptions. If the math says 2.8 contracts, that means 2 contracts, not 3.
Use the table below to map common stop sizes to per-contract risk.
Dollar Risk Per Contract at Common Stop Distances
| Stop Distance | Dollar Risk Per ZB Contract |
|---|---|
| 4 ticks | $125.00 |
| 8 ticks | $250.00 |
| 16 ticks | $500.00 |
| 32 ticks (1 full point) | $1,000.00 |
From there, multiply the per-contract risk by your contract count.
Example: a 16-tick stop on 2 ZB contracts = $500.00 × 2 = $1,000.00 in total risk.
Applying This in Futures Prop Firm Sim Accounts
Size ZB from tick risk, not contract face value. What matters is simple: stop distance × contract count. That’s your trade risk.
A few rules matter here:
- Stay inside your daily loss limit.
- Size from tick risk only.
- Treat margin as an access rule, not a stop-risk rule.
Before you enter, double-check the active month and your order quantity.
What to Check Before Placing a ZB Trade
Once you’ve sized the trade from ticks, do two quick checks before you hit buy or sell: the active contract month and the order ticket. Skip either one, and your risk math can get messed up fast.
Active Contract Month and Rollover
ZB trades on a quarterly cycle: March (H), June (M), September (U), and December (Z). ZB is the root symbol, and the month code tells you which delivery month you’re looking at.
As of September 23, 2026, the active front-month contract is ZBZ26, which is the December 2026 contract.
Don’t just assume your platform switched over cleanly. Check volume and open interest. The front month should be the one with the highest numbers on both. That’s usually the fastest way to spot the contract traders are actually using.
Rollover pushes traders into the next liquid month before expiration. For the December contract, that usually happens in late November. If you chart with a continuous contract, that’s fine for analysis, but don’t place a live order off that symbol. Switch to the exact delivery-month contract first.
Once the month is correct, check how the price is shown on the ticket.
Platform Display and Order Quantity Checks
Make sure your platform is showing ZB in 32nds or decimal format before placing the order. That sounds small. It isn’t. Read the format wrong, and your entry or stop can be off by more than you think.
Also check the Quantity field. It should show the number of contracts, not a dollar figure. Sounds obvious, but bad ticket settings are one of those dumb mistakes that can cost real money.
If you change the contract month or move the stop distance, recalculate the dollar risk. Every time.
What ZB Traders Need to Remember
Before you place a ZB order, lock in three checks. ZB risk starts with tick value: $31.25 per tick and $1,000 per point.
Use that tick value to size risk on every order. Take your stop distance in ticks, then multiply it by $31.25 to get your dollar risk per contract.
Check current CME specs and trading hours on cmegroup.com before you trade. ZB uses a 1/32-point quote format, so make sure your platform shows prices the way you expect and verify the active contract month.
Confirm tick value, contract month, and quote format before every trade. 1 tick = $31.25. 32 ticks = $1,000.
FAQs
How do I read a ZB quote like 115-16?
A ZB quote like 115-16 is read in points and fractions of a point. The number before the dash is the full points. The number after the dash is the fractional part in 32nds.
So 115-16 means 115 and 16/32 points. That’s the standard quote format for Treasury bond futures.
How much can I lose on a ZB trade?
There’s no fixed max loss shown here because the data provided doesn’t include ZB’s tick value or its dollar value per tick.
Your actual loss comes down to a simple math problem:
- how many contracts you take
- where your stop sits
- the contract’s tick value
- commissions
So the rough formula is:
Loss = contracts × stop size in ticks × dollar value per tick + commissions
If you want the exact dollar number for ZB, you’ll need the CME contract specs for that contract.
What contract month should I trade in ZB?
Trade the contract month with the most liquidity. In most cases, that means the front-month contract.
For ZB, that’s usually the contract closest to expiration. That’s where you’ll tend to get the best volume and cleaner fills. No need to get cute with a thinner month unless you have a specific reason.
You can check the current active contract month and the next rollover dates on CME Group. That helps you stay in the busiest contract and avoid drifting into the delivery period unless you mean to hold that long.