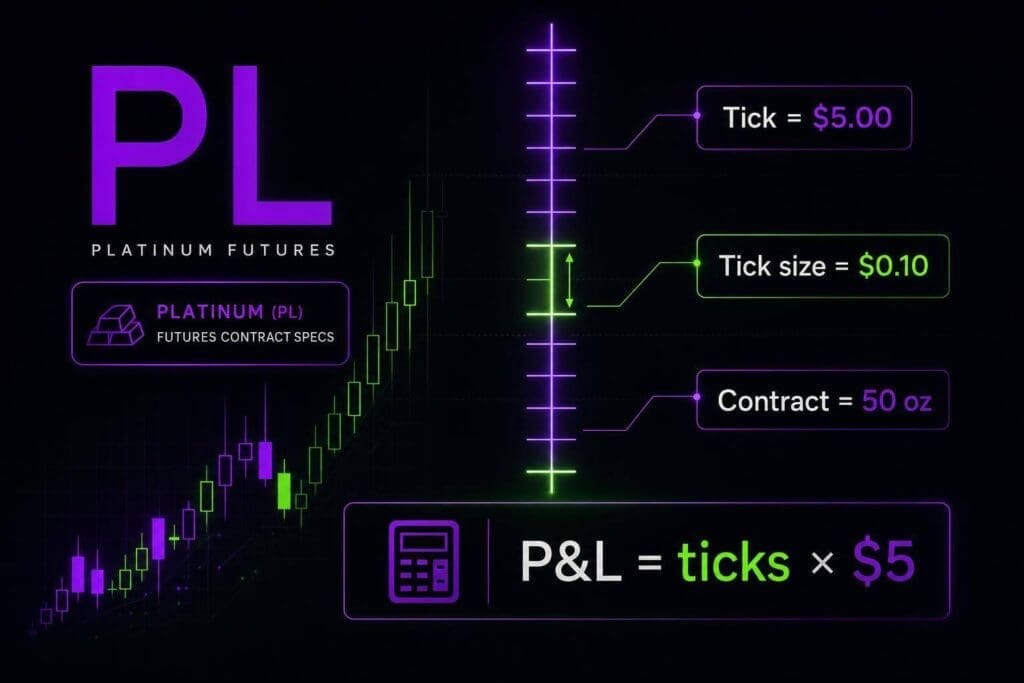
One PL tick is worth $5.00 per contract. That’s the number you need before you touch platinum futures. If your stop is 20 ticks, you’re risking $100 per contract before fees. Simple.
I’ll keep this tight: the only parts that matter are the 50 troy ounce contract size, the $0.10 minimum tick, and how those turn price movement into cash. If you trade PL without that math locked in, you’re guessing on size and giving yourself a bad risk profile. Below, I’ll strip the contract down to the numbers that matter and show how to convert ticks, points, and stops into dollar risk fast.
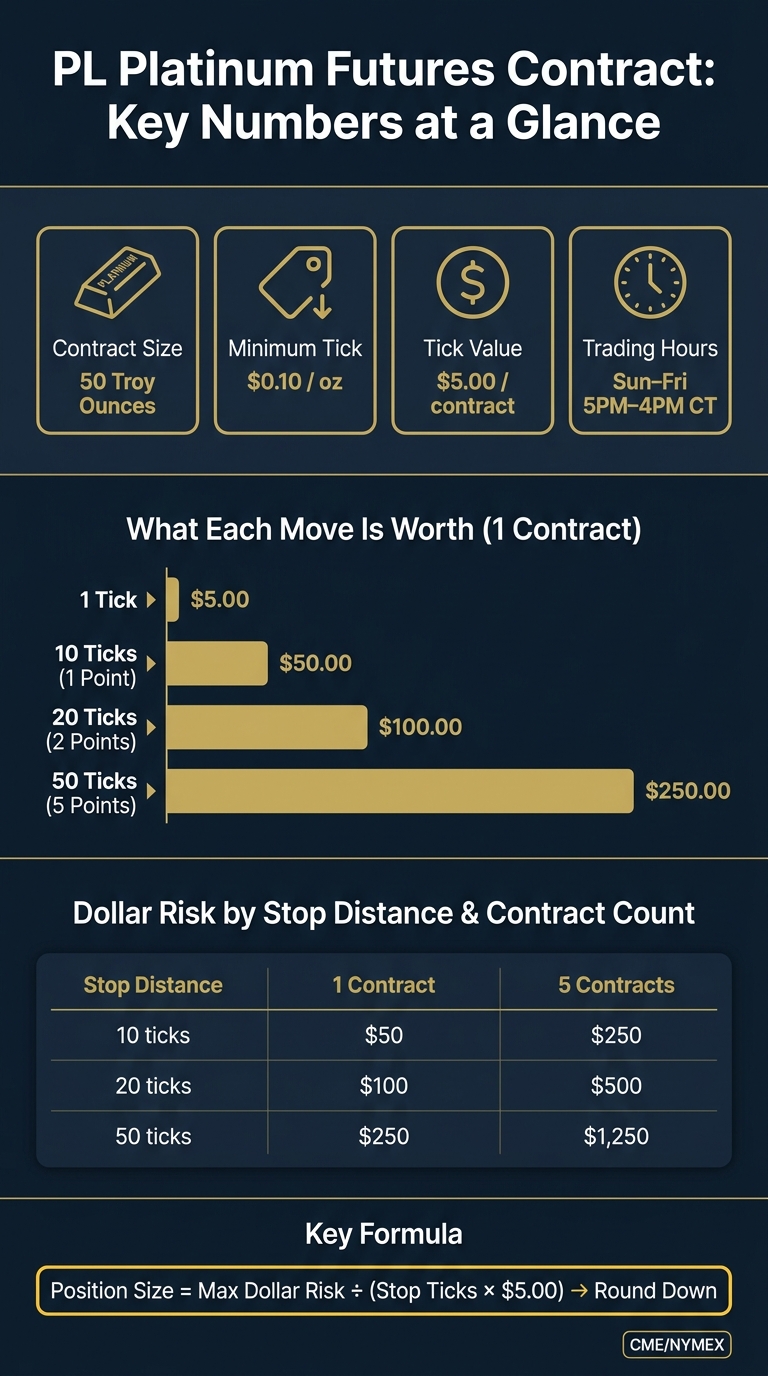
PL Platinum Futures: Tick Value & Risk at a Glance
How to Calculate Profit or Loss on Futures Contracts
sbb-itb-46ae61d
Introduction
PL is the ticker for the platinum futures contract on CME Group‘s NYMEX.[1] This section breaks down the stuff that matters when you’re looking at the contract specs: contract size, quote format, tick size, and tick value.
Core Specs for the PL Platinum Futures Contract
Start with the specs that matter: the ones that control PL pricing and risk per tick. If you trade this contract without knowing these cold, you’re winging it.
PL Contract Snapshot Table
The table below pulls the core specs from CME Group. Dollar figures are in U.S. dollars, and session times use Central Time (CT). Holiday schedules and exchange updates can change the session, so check the latest details on cmegroup.com before you place a trade.
| Specification | Detail |
|---|---|
| Symbol | PL |
| Exchange | NYMEX (CME Group) |
| Contract Size | 50 troy ounces |
| Price Quotation | U.S. dollars per troy ounce |
| Minimum Tick | $0.10 per troy ounce |
| Tick Value | $5.00 per contract |
| Delivery Grade | 0.9995 fineness |
| Electronic Trading Session (Globex) | Sunday–Friday, 5:00 p.m.–4:00 p.m. CT |
For sizing and risk, two numbers do most of the heavy lifting:
- Minimum tick: $0.10 per troy ounce
- Tick value: $5.00 per contract
That’s the math behind every small move in PL.
What a Troy Ounce Means for PL Math
PL is quoted in U.S. dollars per troy ounce, which is the standard unit for precious metals. The part that matters for your P&L is the 50-ounce contract size. That’s the multiplier sitting behind every move.
Example: if platinum is trading at $1,000.00 per troy ounce, one PL contract controls $50,000.00 in notional value:
$1,000.00 × 50 = $50,000.00
That multiplier is the base layer for everything that comes next, from tick value to stop placement to contract count. One small price move can add up faster than newer futures traders expect.
Next, turn those contract specs into actual tick value and dollar risk.
How Much Is One PL Tick Worth?
Use the PL tick value to turn price movement into dollar risk. That’s the number that matters when you’re setting stops or figuring out whether a trade even makes sense.
Tick Size vs. Tick Value
Once you know the contract size, the next job is simple: translate each move in PL into dollars.
Tick size and tick value are not the same thing.
- Tick size is the smallest move PL can make: $0.10 per troy ounce
- Tick value is what that move is worth in dollars: $5.00 per contract
50 troy ounces × $0.10 = $5.00 per tick, per contract[1]
So if your stop is 10 ticks, you’re risking $50.00 per contract.
Also, 1 point = 10 ticks. That means a 1.00-point move is worth $50.00 per contract.
PL Tick-to-Dollar Conversion Table
| Price Move | Ticks | Dollar Value Per Contract |
|---|---|---|
| 1 Tick | 1 | $5.00 |
| 10 Ticks | 10 | $50.00 |
| 1.00 Point | 10 | $50.00 |
| 2.00 Points | 20 | $100.00 |
| 5.00 Points | 50 | $250.00 |
Use this table when you’re mapping stops, targets, and P&L in the next section.
How PL Price Moves Affect Profit and Loss
This is where tick value turns into actual dollars.
PL P&L Formula
P&L = (Exit − Entry) × 50 × contracts
If you’re short, flip it:
P&L = (Entry − Exit) × 50 × contracts
PL moves in dollar terms per ounce, and each 1.00-point move is worth $50.00 per contract. Simple math. No fluff.
Long Trade Example
Buy 1 PL contract at $1,020.00 and sell at $1,021.00.
That’s a 1-point move:
1 point × 50 = $50.00 per contract
Scale it up and the P&L scales right with it. At 5 contracts, that same move pays $250.00. At 10 contracts, it’s $500.00.
The table below shows how that works across size:
| Price Change (per oz) | 1 Contract | 5 Contracts | 10 Contracts |
|---|---|---|---|
| $0.10 (1 tick) | $5.00 | $25.00 | $50.00 |
| $1.00 (1 point) | $50.00 | $250.00 | $500.00 |
| $10.00 (10 points) | $500.00 | $2,500.00 | $5,000.00 |
Short Trade Example
Sell 1 PL contract at $1,020.00 and cover at $1,019.00.
That’s still a 1-point move, so it pays $50.00 per contract. If price goes the wrong way and rises 1 point instead, you lose $50.00. Same math. The sign is the only thing that changes.
Use these dollar amounts when you set stops and decide how many contracts to carry in the next section.
Sizing PL Positions and Stops in Dollar Terms
Now turn that PL tick math into position size and stop risk.
Use the PL tick value to convert your stop distance into dollar risk and figure out how many contracts you can take without blowing past your limit.
Position-Sizing Formula for PL
Use this formula:
Contracts = Maximum Dollar Risk ÷ (Stop Distance in Ticks × $5.00)
Always round down to the nearest whole contract.
Set your max risk first. Then pick the stop distance. The contract count comes after that, not before.
PL Stop-Distance Risk Table
| Stop Distance | Risk (1 Contract) | Risk (2 Contracts) | Risk (5 Contracts) |
|---|---|---|---|
| 5 ticks | $25.00 | $50.00 | $125.00 |
| 10 ticks | $50.00 | $100.00 | $250.00 |
| 15 ticks | $75.00 | $150.00 | $375.00 |
| 20 ticks | $100.00 | $200.00 | $500.00 |
| 50 ticks | $250.00 | $500.00 | $1,250.00 |
Use this table as a quick gut check before you place the order. It saves you from doing math mid-session and taking on more risk than you meant to.
Risk Example for Futures Prop Traders
If your max risk is $300 and the stop is 50 ticks, the math is simple:
$300 ÷ $250 = 1.2 contracts
Round down to 1 contract, which puts your stop risk at $250.00.
If you take 2 contracts, your risk jumps to $500.00, which is over the limit. No gray area there.
Also, don’t treat the stop calculation as your full cost. Commissions, fees, and slippage still hit the trade. Leave yourself a buffer between your tick-based risk and your hard dollar cap.
Next, check PL trading hours and settlement timing before placing the order.
When and Where PL Trades
Once you’ve got PL risk sized, the next job is simple: know when it’s actually trading and when settlement hits.
Exchange and Trading Session Details
PL platinum futures trade on CME Group’s NYMEX [1]. Before you place an order, make sure your broker, platform, and data feed are all set up for PL. Sounds obvious, but this is the kind of basic check that saves dumb mistakes.
PL also has a daily maintenance halt in Central Time, when electronic trading pauses. If you’re planning to hold through that break, don’t guess. Check the exact halt window directly with CME Group first [1].
Regular Trading Hours and Settlement Time
Trading hours and settlement timing affect the numbers you see on screen. That includes settlement values and your end-of-day P&L [1].
Check the settlement time in Central Time before you trade. If you ignore that, your P&L can look off and you’ll be stuck figuring out why after the fact.
Holidays, Expiration, and Rollover
Check CME Group’s holiday calendar, expiration dates, and rollover timing before trading PL so you’re in the active contract month [1]. This matters more than people think. Trading the wrong month is an avoidable mess.
You should also check your funded-account rollover and holiday rules before putting on a trade.
Use these details to verify the contract before you trade.
What to Check Before Trading PL
You’ve already got the contract specs and tick math. Now do the last sanity check before you click buy or sell.
CME Group lists PL with a $0.10 tick size and a $5.00 tick value per contract. That’s the math you use to turn a stop, position size, and trade idea into actual dollar risk before entry. No guessing. No sloppy sizing.
PL Pre-Trade Checklist
Run through these checks before every PL trade:
- Confirm the active contract month. Trading the wrong month can turn into a rollover mess.
- Verify your platform shows $0.10 tick increments. If the symbol settings are off, your sizing and P&L can be wrong from the first click [1].
- Convert your stop to ticks, then multiply ticks × $5.00 × contracts to get dollar risk.
- Add commissions and exchange fees.
- Check CME Group trading hours, settlement, and the holiday calendar [1].
- Confirm your account supports PL trading [1].
Bottom Line
PL moves in $0.10 increments, and each tick is worth $5.00 per contract. Convert your stop and size into dollar risk before entering the trade.
FAQs
How much margin do I need to trade 1 PL contract?
There’s no single fixed margin for 1 platinum futures contract. It changes based on the exchange requirement and the rules set by your broker or prop firm.
Check the official contract specs from the exchange first. Then check your broker’s or prop firm’s margin policy. Those numbers often don’t match. A firm’s day-trading margin can be a lot lower than the exchange’s initial margin, and that matters the second you place the trade.
If you’re trading through a prop firm, use its help center or support docs, not guesswork. Confirm the margin before you enter. Simple, but it saves dumb mistakes.
What is the dollar value of a 20-tick move in PL?
A 20-tick move in PL is simple math: take the contract’s tick value and multiply it by 20.
That’s your P/L for a 20-tick move. No guesswork.
PL specs come from the exchange, not your platform layout or whatever someone posted in a Discord last month. So before you trade it, check the current tick size and tick value on CME Group. If those numbers are off, your profit, loss, and risk math will be off too.
How do I calculate PL position size from my stop?
Start with the dollar amount you’re willing to lose on the trade. That’s your risk cap.
Next, measure your stop-loss in ticks and multiply it by the contract’s P&L tick value. That gives you your risk per contract.
Then divide your total dollar risk by the dollar risk per contract. The result is the max number of contracts you can take.
Simple formula:
Position size = Total dollar risk ÷ (Stop-loss in ticks × Tick value)
One last thing: check the current tick value and contract specs on CME Group before you place the trade. Don’t guess. Contract details matter.